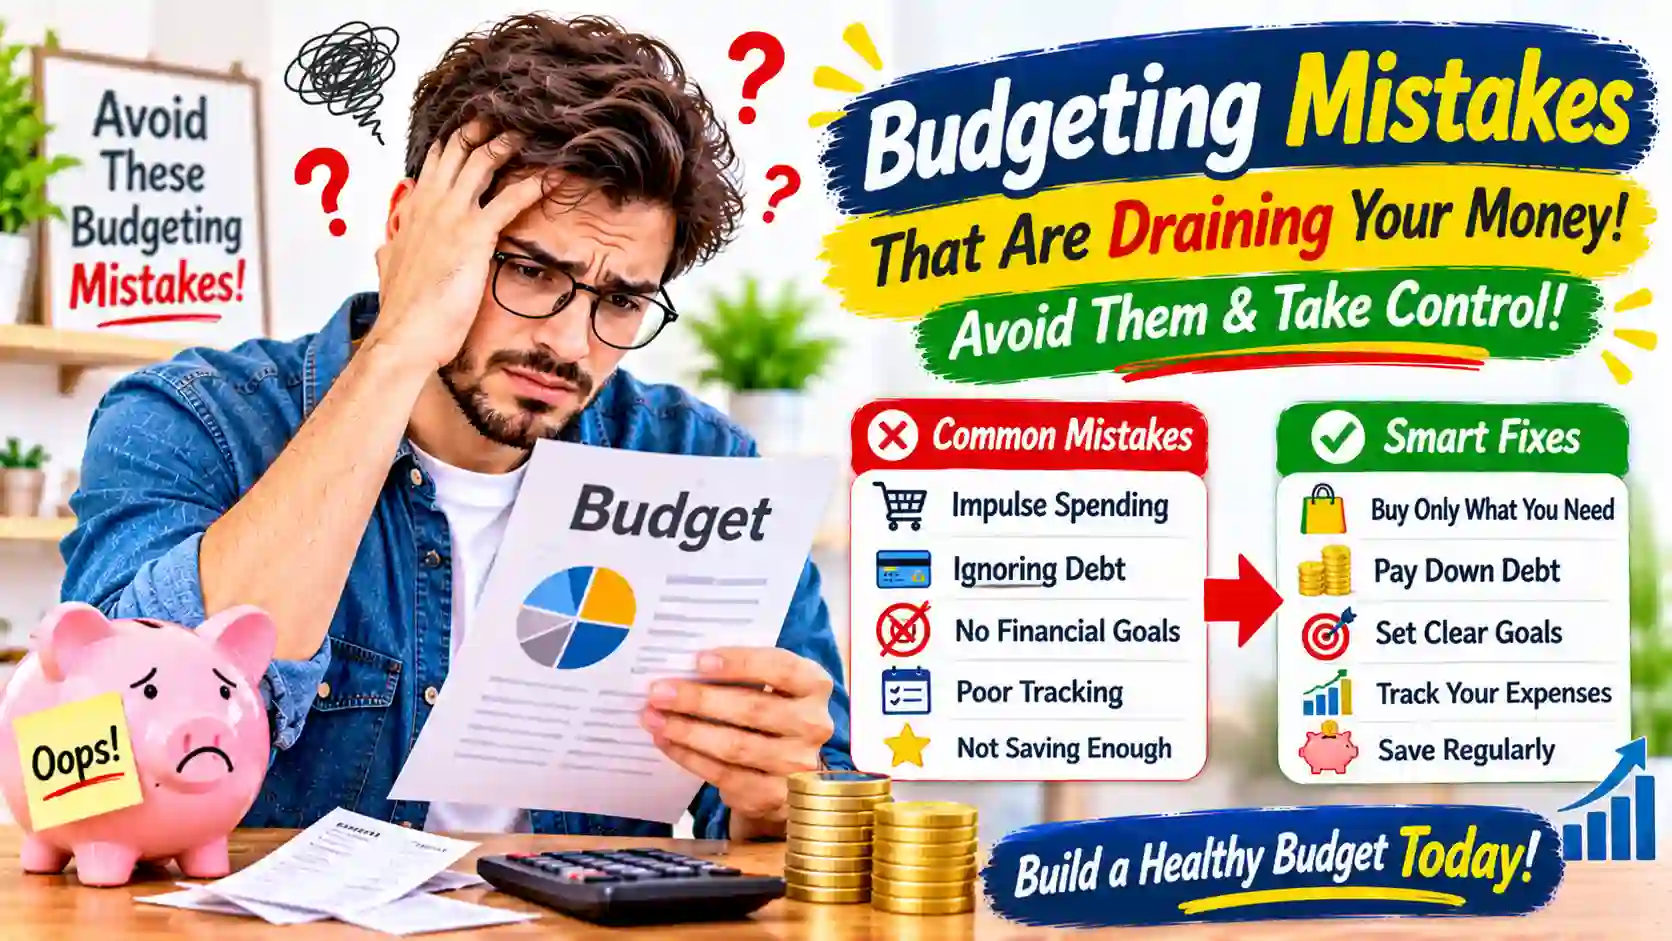
Managing money can become complicated when income, bills, subscriptions, savings and everyday purchases all happen at different times. Without a clear system, it is easy to lose track of spending or forget about upcoming expenses.
A budgeting app can bring much of this information into one place. Depending on the tool, you may be able to categorize purchases, set spending limits, monitor account balances and review your progress toward financial goals.
However, not every budgeting app works the same way. Some focus on assigning every dollar a purpose, while others emphasize automatic transaction tracking, shared household budgeting, or an overall view of your finances.
In this guide, we compare six popular budgeting tools, explain what each one does well and discuss a few limitations to consider before signing up.
In This Article
1. Why Use a Budgeting App?
A budgeting app is a digital tool that helps you organize income, expenses and savings. Instead of relying entirely on memory or scattered notes, you can use one place to review your financial activity.
The right app can make budgeting easier, but it does not automatically improve your spending habits. You still need to review transactions, set realistic limits and make decisions based on your financial priorities.
Understand where your money goes
Many budgeting apps organize transactions into categories such as groceries, housing, transportation, entertainment and utilities. This can help you notice patterns and identify areas where your spending may be higher than expected.
Plan for upcoming expenses
Some apps allow you to create spending plans for regular bills and future purchases. Planning ahead can make expenses such as insurance payments, annual subscriptions and car maintenance easier to manage.
Work toward savings goals
You may be able to set targets for an emergency fund, a vacation, a major purchase, or another personal goal. Seeing your progress can help you stay focused on your plan.
Make household budgeting easier
Some tools offer shared access or household features. These can help partners or family members review spending and coordinate financial responsibilities.
2. 6 Budget Apps to Consider
The following apps use different budgeting approaches. The best choice depends on how you prefer to manage money, which devices you use and whether you want a free or paid tool.
Features, subscription plans, bank connections and regional availability can change. Check each provider's official website for the latest details before creating an account or paying for a subscription.
1. YNAB (You Need A Budget)
YNAB is designed around a zero-based budgeting approach. Instead of simply tracking what you have already spent, it encourages you to assign your available money to specific purposes.
For example, you might assign part of your income to rent, groceries, transportation, debt payments and savings. The goal is to give every available dollar a clear job before you spend it.
What makes YNAB useful?
- Plan how to use available money.
- Create spending categories and targets.
- Review progress toward savings goals.
- Adjust your budget when priorities change.
- Access educational budgeting resources.
Potential limitations
YNAB is a paid budgeting service after its trial period. Its approach may also feel unfamiliar to people who only want a simple expense tracker. You may need some time to learn its budgeting method and maintain your categories regularly.
Best suited for: People who want a structured budgeting routine and are comfortable actively planning where their money goes.
2. Monarch Money
Monarch Money combines budgeting with a broader view of personal finances. It is designed for people who want to organize spending while also reviewing accounts, balances and financial goals.
Depending on supported institutions and account connections, users can bring financial information together and review it through one dashboard.
What makes Monarch Money useful?
- Organize transactions into spending categories.
- Create and review household budgets.
- Monitor connected financial accounts.
- Set and track financial goals.
- Review overall financial information in one place.
Potential limitations
Monarch Money is a subscription-based product. Its connected-account features depend on supported financial institutions and regions. Some users may also find that a broad financial dashboard includes more features than they actually need for basic budgeting.
Best suited for: Individuals or households who want for budgeting and a wider overview of their finances in one service.
3. Rocket Money
Rocket Money focuses on helping users review their finances, monitor recurring expenses and identify subscriptions they may no longer need. It also offers budgeting and spending tracking features.
For people who have several recurring payments, reviewing subscription activity can be a useful starting point for understanding monthly spending.
What makes Rocket Money useful?
- Review spending and financial transactions.
- Identify recurring subscription payments.
- Organize expenses into categories.
- Review account information through its dashboard.
- Access additional money-management features depending on the plan.
Potential limitations
Some features may require a paid plan or additional fees. Subscription cancellation and bill negotiation services may have eligibility requirements and may not be available in every location. Review the terms carefully before using these services.
Best suited for: People who want help reviewing recurring expenses and tracking everyday spending.
4. Goodbudget
Goodbudget uses the envelope budgeting method. This approach divides your available money into separate categories, often called envelopes. Each envelope represents a spending purpose, such as groceries, rent, transport, or entertainment.
Once you have assigned money to an envelope, you can track how much remains in that category. This makes it easier to see when you are approaching a spending limit.
What makes Goodbudget useful?
- Use digital envelopes for spending categories.
- Plan how much money to allocate to each category.
- Track spending against category limits.
- Share a budget with household members.
- Use a manual budgeting approach without relying entirely on automatic tracking.
Potential limitations
The envelope method requires regular attention. Depending on the plan and setup, some features and synchronization options may be limited. People who prefer fully automatic transaction tracking may find manual entry less convenient.
Best suited for: People who prefer visual spending categories and want more control over how their money is allocated.
5. EveryDollar
EveryDollar is a budgeting app built around zero-based budgeting. It encourages users to plan their income and assign money to expenses, savings and other priorities.
Its category-based approach can help people build a monthly spending plan before the month begins. This is useful when you want a clear structure instead of simply reviewing transactions after spending.
What makes EveryDollar useful?
- Create a monthly budget using spending categories.
- Plan income against expected expenses.
- Track progress toward savings goals.
- Review spending against your budget.
- Use a straightforward zero-based budgeting approach.
Potential limitations
Some features may be restricted to paid plans. Automatic bank connections and other services can depend on the subscription and supported financial institutions. Users who prefer a fully automated financial dashboard may want to compare other tools as well.
Best suited for: People who want a structured monthly budget and prefer assigning income to specific spending categories.
6. Empower Personal Dashboard
Empower's Personal Dashboard is useful for people who want a broad view of their financial picture, particularly account balances, investments and net worth.
It can help you review connected financial information and understand how different accounts contribute to your overall financial position.
What makes Empower useful?
- Review financial accounts in one dashboard.
- Monitor net worth and account balances.
- View investment-related information.
- Review spending information and cash flow features.
- Get a broader picture of your finances.
Potential limitations
Empower is more focused on financial visibility and investment tracking than detailed, hands-on category budgeting. People who want envelope budgets or detailed spending plans may prefer a dedicated budgeting app.
Some additional financial services may involve separate eligibility requirements or costs. Review the provider's terms and service details before signing up.
Best suited for: People who want to monitor their broader financial picture, including investments and net worth, alongside spending information.
3. Budget App Comparison
Comparing the main purpose of each app can help narrow your options. The table below summarizes their general focus rather than ranking them from best to worst.
| App | Main Focus | Pricing Approach | Best For |
|---|---|---|---|
| YNAB | Zero-based budgeting | Paid subscription with trial options | Structured budgeting |
| Monarch Money | Budgeting and financial overview | Paid subscription | Household financial planning |
| Rocket Money | Spending and subscriptions | Free and paid features | Recurring expense tracking |
| Goodbudget | Envelope budgeting | Free and paid plans | Category-based spending limits |
| EveryDollar | Zero-based budgeting | Free and paid features | Monthly budget planning |
| Empower | Net worth and investment overview | Free dashboard with other services available | Overall financial visibility |
Pricing, included features and availability can change. A free version may have limitations, while paid plans may include additional services. Always confirm the current terms on the provider's official website.
4. How to Choose the Right Budget App
The right budgeting app is not necessarily the one with the most features. It is the one that fits your financial habits, works with your devices and makes it easier to follow your budget.
Decide what you need the app to do
Start by identifying your main challenge. Do you struggle to track everyday purchases? Do you want to control category spending? Are you trying to manage household expenses or monitor your savings goals?
Write down the two or three features that matter most. This can help you avoid paying for tools you do not need.
Check device compatibility
Some budgeting services support mobile apps and web dashboards, while others have different features across platforms. Check whether the app works on your phone, tablet and computer before choosing it.
Review bank compatibility
If you want automatic transaction imports, check whether the app supports your bank or financial institution. Connections can differ by country and provider and some accounts may require manual updates.
Consider your preferred budgeting method
There are several common approaches:
- Zero-based budgeting: Assign available income to planned expenses, savings and other priorities.
- Envelope budgeting: Allocate money to separate categories and track how much remains in each one.
- Expense tracking: Review spending and account activity to understand where money goes.
- Net worth tracking: Review assets and liabilities to get a broader picture of your finances.
Compare the full cost
Do not look only at the advertised starting price. Check whether the plan renews monthly or annually, whether there is a trial period and whether extra services involve separate charges.
Also consider whether the app offers enough value to justify the cost. If your needs are simple, a free spreadsheet or basic budgeting tool may be sufficient.
5. Free vs. Paid Budgeting Apps
You do not necessarily need a paid app to create a useful budget. Many people can manage their spending with a spreadsheet, a notebook, or a free version of a budgeting service.
When a free app may be enough
A free budgeting tool may work well if you want to record expenses, create basic categories and review your monthly spending. It can also be a good way to learn how to budget before paying for additional features.
When a paid app may be worth considering
A paid service may be useful if it offers features that solve a specific problem for you, such as shared household budgeting, automatic account connections, advanced reports, or detailed savings goals.
Before subscribing, compare the annual cost with the features you expect to use. A subscription should fit your budget rather than become another unnecessary expense.
Do not confuse convenience with necessity
Automatic transaction imports can save time, but they are not essential for everyone. Some people prefer entering transactions manually because it encourages them to pay attention to their spending.
Choose the approach that makes you more consistent, not simply the one that offers the most automation.
6. Privacy and Security Considerations
Budgeting apps may contain sensitive information about your income, purchases, financial accounts and spending habits. Take time to understand how an app handles that information before connecting accounts.
Review the privacy policy
Look for information about what data the provider collects, how it is used, whether it is shared with other companies and how long it is retained.
Understand account connections
Some apps use third-party services to connect financial accounts. Review the permissions requested and understand what information can be accessed.
Use strong account protection
- Use a unique password for your account.
- Enable multi-factor authentication when available.
- Keep your phone and app updated.
- Avoid signing in through suspicious links.
- Review connected accounts and permissions periodically.
Never share your banking password, verification codes, or other confidential information with someone claiming to provide budgeting support.
7. Tips for Getting More From a Budget App
Downloading an app is only the first step. Building a routine around it is what makes the tool useful.
Set up your main categories first
Start with a manageable list of categories: housing, groceries, transportation, utilities, debt payments, personal spending and savings. You can add more detail later if necessary.
Review transactions every week
Set aside a few minutes each week to review new transactions. Check whether purchases have been categorized correctly and whether you are staying within your spending limits.
Plan for irregular expenses
Some costs do not happen every month. Examples include annual insurance premiums, vehicle maintenance, school expenses and holiday spending. Create categories for these costs and set aside money gradually when possible.
Use realistic spending limits
A budget should reflect your actual income and responsibilities. Setting limits that are too restrictive can make the plan difficult to maintain.
Review your budget at the end of each month
Compare your planned spending with your actual spending. Look for patterns and make adjustments where needed. Your budget can change as your income, bills and priorities change.
8. Budgeting App Mistakes to Avoid
Even a well-designed budgeting app cannot make every financial decision for you. Avoid these common mistakes when using one.
Choosing an app only because it is popular
A tool that works well for one person may not suit your needs. Compare features, costs and budgeting methods before deciding.
Ignoring cash purchases
If you only track bank and card transactions, cash purchases may be missing from your budget. Record them manually when necessary, so your spending picture remains useful.
Forgetting to review automatic categories
Automatic categorization can sometimes assign a transaction to the wrong category. Check important transactions and correct mistakes when they occur.
Paying for features you never use
Review your subscription periodically. If you rarely use premium features, consider whether a lower-cost or free option would meet your needs.
Expecting the app to solve every money problem
A budgeting app can help organize information, but it cannot replace a realistic spending plan or decisions about debt, savings and financial priorities.
9. Final Thoughts
The best budgeting app is the one that helps you understand your money and build habits you can maintain. Some people prefer a structured zero-based budget, while others want simple expense tracking or a broader view of their financial accounts.
YNAB and EveryDollar offer structured budgeting approaches. Goodbudget focuses on digital envelopes. Monarch Money combines budgeting with a wider financial dashboard. Rocket Money emphasizes recurring expenses and spending, while Empower is more focused on overall financial visibility and investment tracking.
Take time to compare the features, pricing, privacy practices, and regional availability of each service. If you are unsure, start with a free option or trial where available and see whether the budgeting method suits you.
Most importantly, remember that an app is a tool, not a financial plan by itself. Regularly reviewing your spending and making realistic adjustments are what help turn budgeting into a useful habit.
Financial Disclaimer
This article is for educational and informational purposes only. It does not provide personalized financial, investment, tax, or legal advice. App features, pricing, availability and terms may change. We are not affiliated with or endorsed by the providers mentioned unless explicitly stated. Review each provider's official terms and privacy policy before using a service. Make decisions based on your own needs and circumstances.
Meet the Author
Bruce Lee
Bruce Lee is the author behind Nksaas. He focuses on creating accessible personal finance content covering budgeting, saving, credit basics, side hustles and beginner investing concepts.
Email: info.nksaas@gmail.com