15 Common Budgeting Mistakes and How to Avoid Them
A budget can help you take control of your money, but a few common mistakes can make it difficult to follow. Learn what to avoid and how to create a realistic spending plan that supports your financial goals.
Creating a budget is one of the most useful steps you can take toward better money management. It helps you understand where your money goes, plan for upcoming expenses and make progress toward your financial goals.
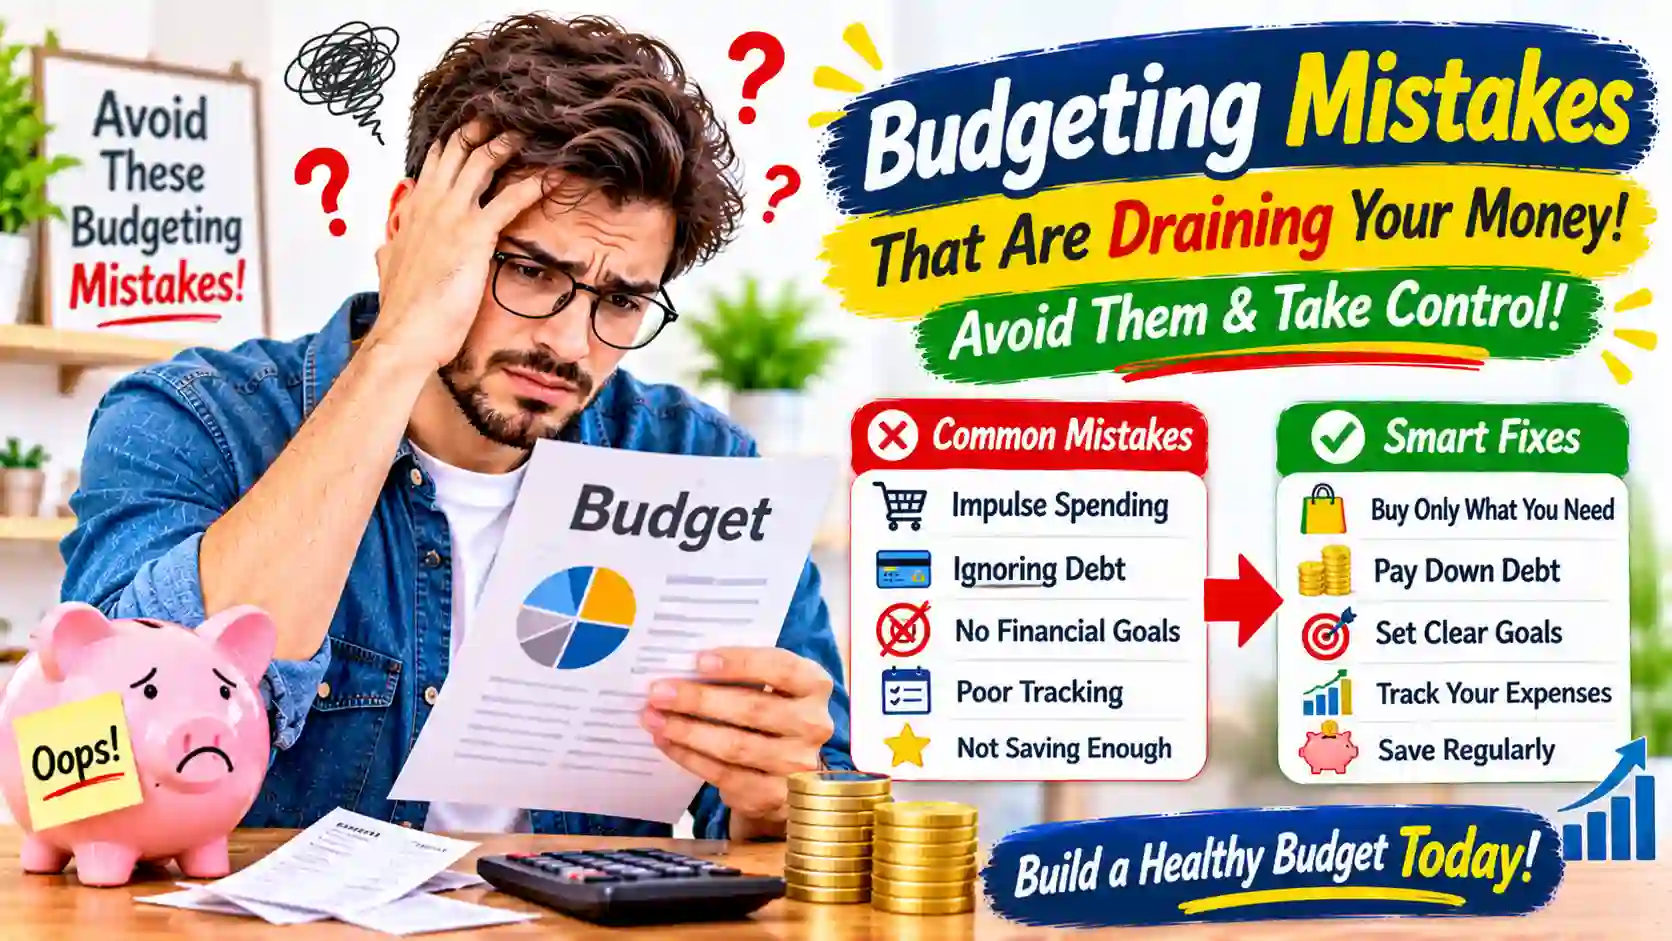
However, having a budget does not automatically guarantee better financial habits. Many people create spending plans that are too restrictive, forget important expenses, or stop tracking their money after a few weeks.
The good news is that most budgeting problems can be corrected with a few practical changes. In this guide, we will explore 15 common budgeting mistakes and explain how to avoid them.
Table of Contents
Why Budgeting Sometimes Fails
A budget usually fails when it does not reflect real life. Someone might plan to spend very little on food, entertainment, or transportation without considering their actual habits and needs.
Unexpected bills, irregular income, forgotten subscriptions, and changing priorities can also make a budget difficult to maintain.
A successful budget should be flexible enough to handle normal life changes while keeping your most important financial priorities in focus. The goal is not to eliminate every enjoyable expense. It is to make informed decisions about your money.
15 Common Budgeting Mistakes and How to Avoid Them
1. Not Tracking Your Spending
One of the biggest budgeting mistakes is estimating expenses instead of tracking them. Small purchases can add up over time, and it is easy to underestimate how much you spend on food, shopping, subscriptions and entertainment.
Without accurate spending information, your budget may be based on assumptions rather than reality.
How to avoid it: Review your bank and credit card transactions regularly. Record cash purchases too and organize expenses into categories. A budgeting app or simple spreadsheet can make this process easier.
2. Setting Unrealistic Spending Limits
Setting extremely low spending limits may look good on paper, but they can be difficult to maintain. For example, reducing your grocery budget dramatically without changing your shopping habits may lead to frustration.
A budget should challenge you without making everyday life unnecessarily difficult.
How to avoid it: Start with your actual spending patterns. Make gradual adjustments to categorize where you can reasonably save money.
3. Forgetting Irregular Expenses
Some expenses do not arrive every month. Annual insurance premiums, vehicle maintenance, school costs, holiday spending, and medical bills can catch you off guard if they are not included in your plan.
How to avoid it: List expenses that happen quarterly, annually, or occasionally. Estimate their yearly cost and divide it by 12 to calculate a monthly savings amount.
For example, if you expect to spend $600 on annual vehicle maintenance, setting aside $50 per month can help you prepare for that expense.
4. Ignoring Small Purchases
A daily coffee, occasional snack, delivery fee, or small online purchase may seem insignificant. However, frequent small purchases can consume a meaningful part of your monthly budget.
How to avoid it: Track small transactions for at least one month. You do not have to stop every small purchase, but understanding the total can help you decide what is worth keeping.
5. Not Having an Emergency Fund
A budget without emergency savings can become difficult to manage when unexpected expenses appear. A car repair, urgent travel, or temporary loss of income may force you to rely on credit cards or borrow money.
How to avoid it: Include a regular emergency savings contribution in your budget, even if you can only afford a small amount at first. Build your savings gradually according to your circumstances.
6. Treating Savings as Whatever Is Left Over
Many people plan to save whatever remains after paying bills and covering daily expenses. Unfortunately, there may be little or nothing left at the end of the month.
How to avoid it: Include savings as a planned budget category. If possible, schedule an automatic transfer shortly after receiving your income. Choose an amount that does not interfere with essential bills.
7. Forgetting About Subscriptions
Streaming platforms, software, memberships, cloud storage and other recurring services can quietly increase monthly expenses. Some people continue paying for subscriptions they rarely use.
How to avoid it: Review recurring payments regularly. Cancel services you no longer need and compare available plans before renewing subscriptions.
8. Not Planning for Debt Payments
Leaving debt payments out of your budget can make your spending plan inaccurate. Credit card balances, personal loans, student loans and other obligations need to be considered.
How to avoid it: List each debt, its required minimum payment, due date and interest rate. Include required payments in your monthly budget and create a realistic plan for paying down additional balances when possible.
9. Being Too Strict With Your Budget
A budget that removes every enjoyable activity can be difficult to follow. If you do not leave room for hobbies, dining out, or occasional entertainment, you may feel restricted and abandon the plan.
How to avoid it: Set aside a reasonable amount for personal spending. Enjoying your money responsibly is part of a sustainable financial plan.
10. Not Adjusting Your Budget When Income Changes
Your financial situation can change because of a new job, reduced working hours, a pay increase, or freelance income. Continuing to use an outdated budget may create problems.
How to avoid it: Update your budget whenever your income changes significantly. If your income decreases, review flexible expenses and prioritize essential bills. If it increases, consider directing part of the difference toward savings or debt repayment.
11. Confusing Wants With Needs
Essential expenses and optional purchases are not always easy to distinguish. For example, basic transportation may be necessary, but an expensive vehicle upgrade may be optional.
How to avoid it: Separate your expenses into needs, wants and financial goals. This makes it easier to identify which categories can be adjusted when money is tight.
12. Not Setting Clear Financial Goals
Budgeting without a purpose can feel like a repetitive task. When you do not know what you are working toward, it may be harder to stay motivated.
How to avoid it: Choose specific goals, such as building emergency savings, reducing credit card debt, saving for a major purchase, or preparing for retirement. Give each goal a target amount and a realistic timeline.
13. Relying Only on Memory
Trying to remember every bill, payment date and spending category can lead to missed payments and inaccurate records.
How to avoid it: Use a calendar, spreadsheet, budgeting app, or banking alerts to keep track of important financial information. Choose a system you can maintain consistently.
14. Comparing Your Budget With Other People
Someone else's budget may not work for your situation. People have different incomes, household sizes, locations, responsibilities and financial priorities.
How to avoid it: Build your budget around your own circumstances. General budgeting rules can provide a starting point, but your actual needs should guide your decisions.
15. Giving Up After One Bad Month
Unexpected expenses or overspending can cause a monthly budget to go off track. Some people respond by abandoning the entire plan.
One difficult month does not mean budgeting has failed. A budget is a tool that should change as your circumstances change.
How to avoid it: Review what happened, identify the reason for overspending and make reasonable adjustments for the next month. Focus on long-term consistency rather than perfection.
How to Create a Better Budget
Once you understand common budgeting mistakes, you can build a spending plan that is easier to follow. Use these steps to create a practical monthly budget.
Step 1: Calculate Your Monthly Income
Start by identifying how much money you receive after taxes and other payroll deductions. If you have an irregular income, consider using a conservative estimate based on your recent earnings.
Step 2: List Your Essential Expenses
Write down necessary expenses such as housing, utilities, groceries, transportation, insurance and required debt payments. Use actual bills and recent transactions where possible.
Step 3: Include Flexible Spending
Add categories for entertainment, dining out, shopping, hobbies and other non-essential spending. Give these categories realistic limits rather than removing them completely.
Step 4: Plan for Savings and Irregular Costs
Decide how much you can reasonably contribute toward emergency savings and other financial goals. Also include monthly amounts for expenses that do not occur every month.
Step 5: Compare Income With Expenses
Subtract your planned expenses and savings contributions from your take-home income. If the result is negative, review flexible categories and look for adjustments. If money remains, decide how to use it intentionally.
Step 6: Review and Adjust
Track your actual spending and compare it with your plan. Adjust categories when your needs or financial circumstances change.
How Often Should You Review Your Budget?
Reviewing your budget regularly helps you identify problems before they become bigger financial challenges.
- Weekly: Check recent transactions and see whether your spending is within your planned limits.
- Monthly: Compare planned expenses with actual spending and prepare the next month's budget.
- When circumstances change: Update your budget after major changes in income, housing costs, family responsibilities, or debt payments.
- Annually: Review larger financial goals, recurring expenses, insurance needs and savings priorities.
You do not need to spend hours reviewing your finances. A short, consistent check-in can help you stay informed and make better decisions.
Practical Tips for Staying on Track
Avoiding budgeting mistakes becomes easier when you build simple routines around your money.
- Choose a budgeting method that matches your lifestyle.
- Use automatic payments carefully to reduce the risk of missed bills.
- Set reminders for important payment dates.
- Keep emergency savings separate from everyday spending money.
- Review subscriptions and recurring charges regularly.
- Set realistic spending limits for each category.
- Celebrate progress toward meaningful financial goals.
- Adjust your budget instead of abandoning it when plans change.
Final Thoughts
Budgeting is not about controlling every dollar perfectly. It is about understanding your money, planning for important expenses and making spending decisions that support your priorities.
Avoiding common mistakes such as unrealistic spending limits, forgotten expenses and inconsistent tracking can make budgeting much easier. Start with a simple plan, review it regularly and make adjustments when necessary.
Remember that building better financial habits takes time. Focus on steady progress and create a budget that works with your real life.
Frequently Asked Questions
1. What is the most common budgeting mistake?
One common mistake is creating a budget without tracking actual spending. When you rely on estimates, you may overlook small purchases, recurring bills, or irregular expenses.
2. Why do most people struggle to stick to a budget?
People may struggle because their budgets are too restrictive, unrealistic, or difficult to maintain. Unexpected expenses and changing income can also make a budget harder to follow.
3. How can I fix a budget that is not working?
Review your recent transactions, identify categories where actual spending differs from your plan and make realistic adjustments. You may also need to include forgotten expenses or revise savings targets.
4. Should I include entertainment in my budget?
Yes. Including a reasonable entertainment allowance can make your budget more realistic and easier to maintain. The amount should fit your income and essential financial responsibilities.
5. How much money should I save each month?
The right amount depends on your income, essential expenses, debt and financial goals. Start with an affordable contribution and increase it when your circumstances allow.
6. Is it better to use a budgeting app or a spreadsheet?
Both can work. Budgeting apps may automate some tracking tasks, while spreadsheets offer more flexibility and control. Choose the option you are most likely to use consistently.
7. What should I do if I overspend in one category?
Review why the overspending happened and decide whether you can adjust another flexible category or change your future spending plan. Avoid ignoring the problem or abandoning your entire budget.
8. Can I change my budget every month?
Yes. Your budget should reflect your current income, expenses, and priorities. Review it monthly and make adjustments when your circumstances change.
Meet the Author
Bruce Lee
Bruce Lee is the author behind Nksaas. He focuses on creating accessible personal finance content covering budgeting, saving, credit basics, side hustles and beginner investing concepts.
Email: info.nksaas@gmail.com