How Compound Interest Works: A Beginner's Guide
Discover how interest can earn additional interest over time, why starting early matters, and how compounding can influence your savings and investments.
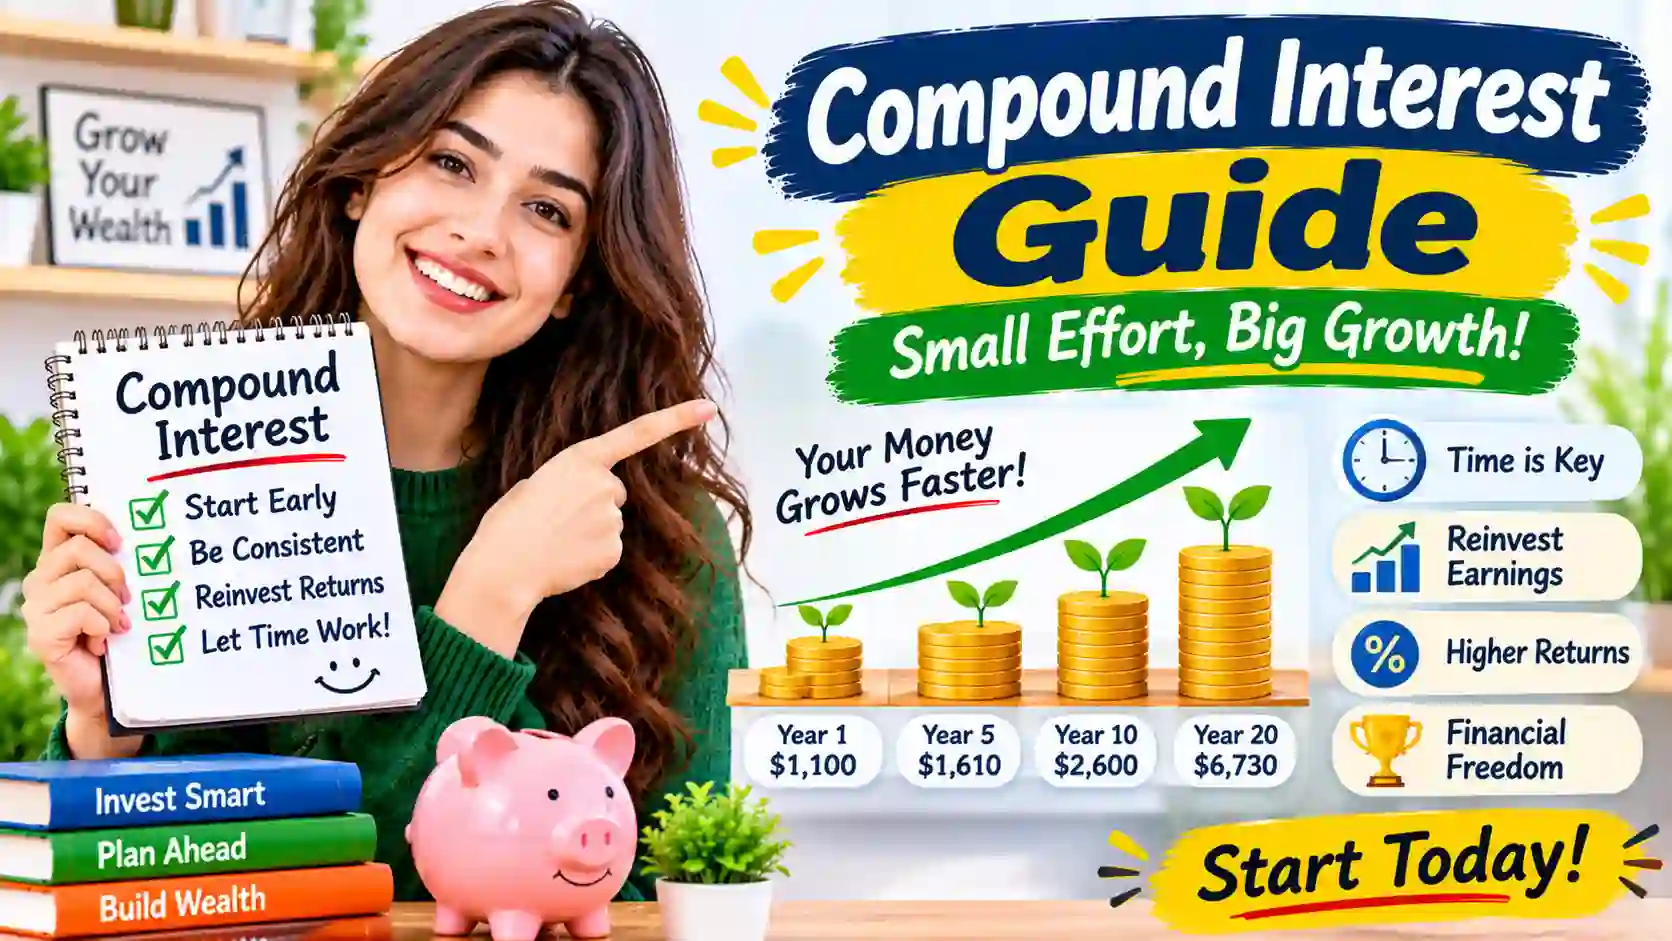
Compound interest is one of the most important concepts to understand when learning about saving and investing. It describes how interest can build on both your original money and the interest already added to it.
Unlike simple interest, which is calculated only on the original principal, compound interest can create a cycle of growth. As time passes, the amount earning interest may become larger, assuming the interest remains in the account or investment.
This is why time can play an important role in long-term saving and investing. However, compound interest does not guarantee profits. Actual results depend on the interest rate or investment return, fees, taxes, inflation, and other conditions.
1. What Is Compound Interest?
Compound interest is interest calculated on an initial amount of money plus interest accumulated during previous periods.
Imagine depositing $1,000 into a savings account that pays 5% annual interest. If interest is added to your balance and remains there, the next year's interest is calculated on the new balance rather than only the original $1,000.
This creates a compounding effect. Each period's interest becomes part of the balance that can earn interest in later periods.
A simple example
- Starting balance: $1,000
- Annual interest rate: 5%
- Interest after year one: $50
- New balance: $1,050
- Interest after year two: $52.50
- New balance: $1,102.50
In the second year, you earn $52.50 rather than $50 because the original interest has become part of the balance.
2. How Does Compound Interest Work?
Compounding happens when earned interest stays in an account or investment and becomes part of the amount used to calculate future returns.
The process repeats over time:
- You deposit or invest an initial amount.
- The account or investment earns interest or a return.
- The earnings remain in the account or investment.
- Future interest is calculated using the updated balance.
- The process continues during each compounding period.
The effect can become more noticeable over longer periods. This is why saving consistently and allowing earnings to remain invested may be helpful for long-term financial goals.
3. Compound Interest vs. Simple Interest
The main difference between simple and compound interest is how the interest is calculated.
Simple interest
Simple interest is calculated only on the original principal. The amount of interest earned in each equal period remains the same when the rate and principal do not change.
For example, $1,000 earning 5% simple interest per year generates $50 each year. After three years, the total interest is $150, giving you a balance of $1,150.
Compound interest
Compound interest is calculated on the principal and previously accumulated interest. Assuming a 5% annual rate with annual compounding, the balance grows as follows:
| Year | Simple Interest Balance | Compound Interest Balance |
|---|---|---|
| Starting amount | $1,000.00 | $1,000.00 |
| Year 1 | $1,050.00 | $1,050.00 |
| Year 2 | $1,100.00 | $1,102.50 |
| Year 3 | $1,150.00 | $1,157.63 |
In this example, compound interest produces a higher balance because each year's interest is added to the amount earning interest. Actual account terms may use different rates and compounding schedules.
4. Compound Interest Formula
You can estimate compound growth using a mathematical formula. The standard formula for a fixed rate with regular compounding is:
A = P (1 + r/n)nt
Where:
- A: Final balance after compounding.
- P: Initial principal or starting amount.
- r: Annual interest rate written as a decimal.
- n: Number of compounding periods per year.
- t: Number of years.
Formula example
Suppose you deposit $2,000 into an account with a fixed annual interest rate of 4%, compounded annually, for five years.
- Principal (P): $2,000
- Annual rate (r): 0.04
- Compounding periods (n): 1
- Time (t): 5 years
Using the formula:
A = 2,000 × (1 + 0.04/1)1 × 5
The estimated ending balance is approximately $2,433.31. That represents about $433.31 in interest before any applicable taxes or fees.
This example assumes the rate stays fixed and interest is compounded annually. A real account may have a variable rate or different terms.
5. How Often Can Interest Compound?
Compounding frequency describes how often earned interest is added to the balance. Depending on the financial product, interest may compound daily, monthly, quarterly, annually, or on another schedule.
When the annual rate is the same and all other conditions are equal, more frequent compounding generally produces a slightly higher balance.
| Frequency | Compounding Periods Per Year |
|---|---|
| Annually | 1 |
| Semi-annually | 2 |
| Quarterly | 4 |
| Monthly | 12 |
| Daily | Usually 365 or 366, depending on the method |
Do not compare accounts using compounding frequency alone. Check the annual percentage yield (APY), fees, minimum balance requirements, withdrawal rules, and whether the advertised rate is fixed or variable.
6. Why Time Matters With Compound Interest
Time gives accumulated interest more opportunities to earn additional interest. This is one reason people often start saving and investing early when possible.
Consider two hypothetical savers. Both receive the same assumed annual return and leave their money invested, but one starts earlier. The earlier saver has more time for compounding to take place.
An illustrative comparison
Imagine two people each invest $5,000 as a one-time contribution:
- Person A invests at an assumed 6% annual return for 30 years.
- Person B invests at the same assumed 6% annual return for 20 years.
With annual compounding and no additional contributions, taxes, or fees:
- Person A: Approximately $28,717 after 30 years.
- Person B: Approximately $16,036 after 20 years.
The difference comes from the additional ten years of compounding. These figures are hypothetical examples, not forecasts or guaranteed investment results. Actual investment returns fluctuate and may be negative.
7. How Regular Contributions Can Increase Growth
You do not need to make one large deposit to benefit from compounding. Regular contributions can help build your savings or investment balance over time.
For example, you might contribute a fixed amount each month to an eligible savings or investment account. As your balance grows, interest or investment returns may be earned on both your original contributions and accumulated earnings.
Regular contributions can also help make saving a consistent habit. However, the final result depends on contribution timing, rates or returns, fees, taxes, and market conditions.
Practical ways to contribute consistently
- Set a monthly savings or investment target.
- Automate transfers when your income arrives.
- Increase contributions when your income grows, if affordable.
- Review your budget to find expenses you can reduce.
- Keep an emergency fund separate from long-term investments.
8. Where Can Compound Interest Help?
Compounding can affect different financial products. Understanding how it applies to each one can help you make better financial decisions.
High-yield savings accounts
Some savings accounts pay interest that is added to your balance. If the interest remains in the account, future interest may be calculated on the larger balance. Compare the annual yield, account fees, withdrawal conditions, and deposit protection available in your country.
Certificates of deposit and fixed-term deposits
Some banks offer fixed-term savings products that pay interest according to specific terms. The compounding method, rate, early withdrawal rules, and renewal conditions can vary.
Retirement accounts
Retirement accounts may hold investments that generate returns over time. Reinvested dividends, interest, and capital gains can contribute to compounding, depending on the investments and account rules. Tax treatment varies by country.
Dividend reinvestment
Some investors choose to reinvest dividends instead of receiving them as cash. Reinvested dividends can purchase additional shares, which may generate future dividends if the company or fund continues making distributions.
Dividend payments and investment values are not guaranteed. Reinvestment does not remove market risk.
9. Compound Interest Can Also Work Against You
Compounding is not always beneficial. It can also increase the amount you owe when interest is added to outstanding debt.
Some credit card and loan balances can accumulate interest when payments do not cover the interest and principal due. The exact calculation depends on the lender's terms, payment timing, fees, and applicable laws.
Why debt can become expensive
- High interest rates can make borrowing more expensive.
- Paying only the minimum may extend repayment time.
- Fees and missed payments can increase the amount owed.
- Continuing to borrow while carrying a balance can make repayment harder.
Review your statements, understand your interest rate, and consider paying more than the minimum when possible. If debt feels difficult to manage, contact your lender or a reputable debt advice service to understand available options.
10. Common Compound Interest Mistakes to Avoid
Understanding compounding is useful, but incorrect assumptions can lead to unrealistic expectations. Avoid these common mistakes:
- Expecting guaranteed growth: Investment returns are uncertain and can be negative.
- Ignoring fees: Account and investment costs can reduce your overall results.
- Forgetting inflation: A higher account balance does not necessarily mean higher purchasing power.
- Withdrawing earnings frequently: Removing interest or returns reduces the amount available to compound.
- Using unrealistic rates: Do not assume unusually high returns will continue indefinitely.
- Ignoring debt interest: High-cost borrowing can work against your financial progress.
- Not checking account terms: Rates, compounding schedules, and withdrawal conditions differ.
11. How to Make Compounding Work in Your Favor
You cannot control every interest rate or investment return, but you can develop habits that support long-term financial progress.
- Start when you can: Even modest contributions may have more time to compound when started earlier.
- Contribute consistently: Regular saving can gradually increase your balance.
- Compare rates and fees: Understand the real costs and returns of financial products.
- Reinvest when appropriate: Keeping eligible earnings invested can support compounding.
- Manage high-interest debt: Reducing expensive debt can improve your financial position.
- Stay patient: Compounding generally becomes more noticeable over longer periods.
- Review your goals: Make sure your savings and investment choices still fit your needs.
12. Final Thoughts
Compound interest is a simple concept with an important long-term effect: earnings can generate additional earnings when they remain in an account or investment.
Starting early, contributing consistently, understanding fees, and allowing time for growth may help you make better use of compounding. At the same time, remember that interest rates can change, investments can lose value, and inflation can reduce purchasing power.
Focus on building a realistic financial plan rather than chasing unusually high returns. Small, consistent steps can help you develop stronger saving and investing habits.
Frequently Asked Questions
1. What is compound interest in simple words?
Compound interest means earning interest on your original money and on interest that has already been added to your balance. This can help savings grow faster over time when earnings remain in the account.
2. How often does compound interest grow?
It depends on the financial product. Interest may compound daily, monthly, quarterly, annually, or on another schedule. Check the product terms to understand exactly how interest is calculated and added.
3. Is compound interest better than simple interest?
For a saver earning interest at the same stated rate over the same period, compound interest can produce a higher balance because accumulated interest also earns interest. The result depends on the terms and costs of the product.
4. Can compound interest make you wealthy?
Compounding can support long-term wealth building, especially when combined with consistent saving and suitable investing. However, it does not guarantee wealth or investment profits. Your results depend on contributions, rates of return, fees, taxes, inflation, and risk.
5. Is compound interest calculated monthly or yearly?
It can be calculated using different schedules, including monthly, daily, quarterly, and yearly compounding. The schedule depends on the account or investment terms.
6. Does compound interest apply to investments?
The concept can apply to investment growth when earnings such as dividends or interest are reinvested. Investment returns are variable and are not the same as guaranteed bank interest.
7. Can compound interest increase credit card debt?
Interest on unpaid credit card balances can increase the amount you owe, depending on the card agreement and payment history. Check your card's APR, billing terms, and interest calculation method.
8. What is the easiest way to benefit from compound interest?
Start saving or investing when your financial situation allows, contribute consistently, understand fees, and avoid unnecessary withdrawals. Choose products that match your goals and risk tolerance.
Meet the Author
Bruce Lee
Bruce Lee is the author behind Nksaas. He focuses on creating accessible personal finance content covering budgeting, saving, credit basics, side hustles and beginner investing concepts.
Email: info.nksaas@gmail.com