Retirement Savings Guide: How to Plan for Your Future
Learn how to estimate your retirement needs, choose suitable savings options, and build a realistic long-term plan for greater financial flexibility.
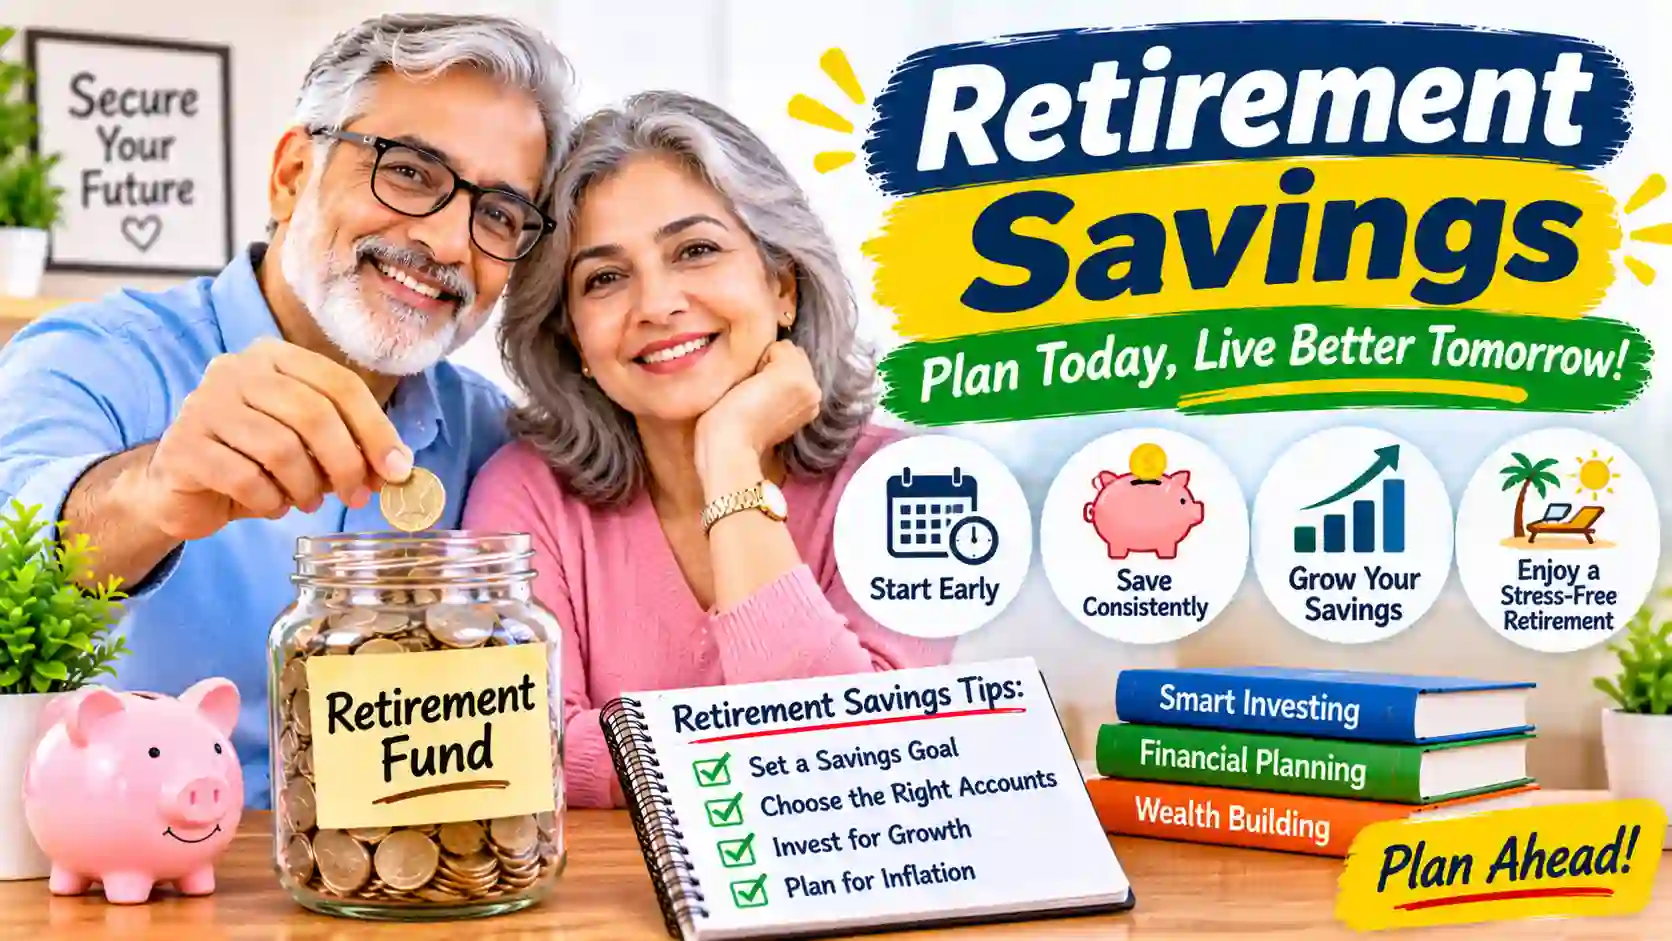
Retirement may feel far away, especially when you are managing everyday expenses, paying off debt, or saving for other goals. However, preparing early can give you more time to build savings and make adjustments as your financial situation changes.
Retirement planning is not simply about reaching one large savings number. It involves estimating future expenses, understanding potential income sources, choosing appropriate savings accounts, and deciding how to invest money based on your goals and risk tolerance.
The right plan looks different for everyone. Your age, location, expected retirement date, lifestyle, health needs, family responsibilities, and access to employer or government retirement programs can all affect your strategy.
1. Why Is Retirement Planning Important?
Retirement planning helps you prepare for a time when you may no longer receive regular employment income. Your savings and other income sources may need to cover housing, food, healthcare, transportation, taxes, and personal expenses.
Without a plan, it can be difficult to know whether your current savings habits are enough to support your future needs.
Benefits of planning ahead
- More time to save: Starting earlier gives your contributions more time to grow.
- Better financial awareness: Estimating future costs helps you understand your savings needs.
- More flexibility: A savings plan may give you more options about when and how you retire.
- Preparation for unexpected costs: Planning can help you consider healthcare and other uncertain expenses.
- Less dependence on one income source: Savings and investments may supplement pensions or government benefits.
2. How Much Should You Save for Retirement?
There is no single retirement savings target that works for everyone. The amount you may need depends on your expected lifestyle, retirement age, location, inflation, health expenses, and other sources of income.
Instead of choosing an arbitrary target, begin by estimating how much you might spend each month after leaving full-time work.
Estimate your future retirement expenses
Consider the main costs you may have during retirement:
- Housing costs, rent, or property maintenance.
- Food, utilities, and everyday household expenses.
- Healthcare, insurance, and prescription costs.
- Transportation and travel.
- Taxes and financial obligations.
- Leisure activities and personal spending.
- Support for family members, if applicable.
Some expenses may decrease after retirement, while others, particularly healthcare costs, may increase. Your estimate should reflect the lifestyle you realistically expect.
A simple monthly expense example
Suppose someone estimates that they may need $3,000 per month in retirement, expressed in today's purchasing power.
- Estimated monthly expenses: $3,000
- Estimated annual expenses: $36,000
This is only a starting point. You would also need to consider inflation, expected pension income, government benefits, taxes, investment returns, and how long retirement may last.
3. Start Saving as Early as You Can
Starting early can give your retirement savings more time to benefit from compound growth. When earnings remain invested, they may generate additional earnings in future periods.
This does not mean you must save a large amount immediately. A manageable contribution that fits your budget can be a useful starting point.
Why starting early can help
- Your contributions have more time to accumulate.
- Compounding may have more time to influence growth.
- You may have more flexibility to adjust contributions over time.
- You can gradually develop a consistent saving habit.
If you are starting later, do not assume retirement planning is pointless. Review your options, set realistic targets, and consider increasing contributions when your financial situation allows.
4. Understand Your Retirement Savings Accounts
Different countries offer different retirement savings systems. Some accounts provide tax advantages, employer contributions, or specific withdrawal rules. Others are designed for personal long-term saving.
Before opening an account, check its eligibility requirements, tax treatment, contribution limits, withdrawal restrictions, investment choices, and fees.
Employer-sponsored retirement plans
Some employers offer workplace retirement plans that allow employees to contribute part of their income. In certain plans, employers also make contributions based on employee participation or contribution levels.
If your employer offers matching contributions, understand the matching formula, eligibility requirements, vesting schedule, and contribution limits. An employer match can be a valuable part of your overall compensation.
Individual retirement accounts
Some countries provide individual retirement accounts with special tax treatment. For example, the United States has account types such as traditional and Roth IRAs, each with different tax and eligibility rules.
These specific account types are not available everywhere. Research the retirement account options and regulations in your own country.
Personal pension and retirement plans
Depending on your location, you may have access to personal pension schemes, private retirement plans, or long-term savings products. Compare their costs, investment choices, withdrawal conditions, and provider regulations before committing.
5. Include Government and Pension Benefits
Your retirement income may come from more than personal savings. Depending on your country and employment history, you may qualify for government retirement benefits, public pensions, or employer-provided pensions.
These programs have different eligibility rules, payment calculations, and retirement ages. Do not assume you will receive a particular benefit without checking your official records.
What to review
- Your estimated government retirement benefit, if available.
- Your eligibility and contribution history.
- Any pension benefits from current or previous employers.
- Rules about early or delayed retirement.
- How benefits may be affected by taxes or other income.
Use official government or pension-provider resources to obtain current information rather than relying on general estimates.
6. Choose Investments That Match Your Goals
Retirement savings may be held in cash accounts, fixed-income products, mutual funds, exchange-traded funds, stocks, bonds, or other eligible investments.
Each option has different risks, potential returns, costs, and liquidity. The right mix depends on your time horizon, financial circumstances, and ability to tolerate investment losses.
Stocks and stock funds
Stocks represent ownership in companies. Stock funds can provide exposure to multiple businesses through one investment. They may offer long-term growth potential but can experience significant price declines.
Bonds and bond funds
Bonds are debt investments issued by governments, companies, or other organizations. They may provide interest income, but they carry risks such as interest-rate risk, inflation risk, and credit risk.
Index funds and ETFs
Index funds and many ETFs follow a market index or another investment strategy. Some provide broad diversification and relatively low ongoing costs, although fees, holdings, and risk levels vary.
Cash and savings products
Savings accounts and certain cash products can provide liquidity and lower volatility than many market investments. However, their returns may not keep pace with inflation over long periods.
Avoid choosing investments based only on recent performance. Review their objectives, risks, fees, and suitability for your retirement timeline.
7. Understand Asset Allocation and Risk
Asset allocation means dividing your portfolio among different types of investments, such as stocks, bonds, and cash.
Your allocation can influence how much your portfolio fluctuates and how it may respond to changing economic conditions.
Factors to consider
- Time horizon: How many years remain before you expect to use your retirement savings?
- Risk tolerance: How comfortable are you with temporary or substantial declines?
- Financial capacity: Can your income and savings absorb investment losses?
- Other income: Will you have pensions or other reliable income sources?
- Liquidity needs: How much money might you need access to in the near future?
Some investors gradually adjust their portfolios as retirement approaches, but there is no universal allocation that suits everyone. A diversified portfolio can still lose money, and lower-risk investments also have limitations.
8. Automate Your Retirement Contributions
Automation can make retirement saving more consistent. Instead of relying on remembering to transfer money each month, you can arrange recurring contributions where your account provider supports them.
How to automate your savings
- Choose an affordable contribution amount.
- Set a recurring transfer date that matches your income schedule.
- Confirm that the money reaches the correct retirement account.
- Review contributions periodically and adjust when your budget changes.
If you receive a pay increase, bonus, or additional income, consider whether you can increase your retirement contributions without compromising essential expenses or emergency savings.
9. Remember the Impact of Inflation
Inflation means that prices generally rise over time, reducing the purchasing power of money. A retirement budget that seems sufficient today may not cover the same lifestyle many years from now.
For example, if your annual expenses are $30,000 today, they may be higher in the future even if your lifestyle stays the same.
This is why retirement planning should consider future purchasing power rather than relying only on today's prices.
Ways to account for inflation
- Review your retirement expense estimate regularly.
- Use realistic inflation assumptions when making projections.
- Understand whether your pension benefits adjust for inflation.
- Consider how your investment mix may support long-term goals.
- Avoid treating historical returns as guaranteed future results.
10. Manage Debt Before Retirement
Carrying large debt balances into retirement can place pressure on a fixed or reduced income. Interest payments may limit the money available for everyday expenses and healthcare.
Managing debt during your working years can help create more flexibility later.
Practical debt management steps
- List all outstanding debts and their interest rates.
- Prioritize expensive debt where appropriate.
- Build a realistic repayment plan.
- Avoid taking on unnecessary new borrowing.
- Review mortgage and other long-term obligations before retirement.
You do not necessarily need to delay all retirement saving until every debt is paid off. Consider your employer retirement benefits, interest rates, emergency savings, and overall financial priorities when deciding how to divide your money.
11. Review Your Retirement Plan Regularly
A retirement plan should change as your life changes. Your income, family responsibilities, health, goals, and expected retirement date may not remain the same.
Reviewing your plan at least once a year can help you identify gaps and make adjustments before they become more difficult to address.
Annual retirement planning checklist
- Check your retirement account balances.
- Review contribution amounts and available employer matching.
- Update your expected retirement expenses.
- Check investment fees and portfolio allocation.
- Review pension and government benefit estimates.
- Update beneficiaries where necessary.
- Consider changes in your tax situation.
- Adjust your savings target if your circumstances change.
12. Common Retirement Savings Mistakes to Avoid
Retirement planning can become harder when small mistakes are repeated over many years. Being aware of these issues can help you make more informed decisions.
- Starting without a target: Estimate your future needs instead of saving without a clear objective.
- Delaying contributions unnecessarily: Waiting can reduce the time available for potential compounding.
- Ignoring employer contributions: Understand any matching benefits available through your workplace.
- Taking excessive risk: Choose investments that reflect your financial situation and risk tolerance.
- Being too conservative without a plan: Low-risk savings may struggle to keep pace with inflation over long periods.
- Ignoring fees: Account and investment charges can reduce your long-term balance.
- Withdrawing retirement savings early: Early withdrawals may reduce future growth and trigger taxes or penalties.
- Forgetting healthcare expenses: Medical and insurance costs may be a significant part of retirement spending.
- Never reviewing your plan: A strategy that once worked may no longer fit your circumstances.
13. When Should You Seek Professional Advice?
Retirement planning can involve complicated tax rules, investment decisions, pensions, estate planning, and withdrawal strategies. A qualified financial professional may help you understand these issues and develop a plan based on your circumstances.
Consider seeking professional guidance if you:
- Have multiple retirement accounts or pension arrangements.
- Are approaching retirement and need a withdrawal strategy.
- Have complex tax or cross-border financial circumstances.
- Need help estimating retirement income and expenses.
- Are unsure how much investment risk is appropriate.
Check the professional's qualifications, regulatory status, compensation structure, and potential conflicts of interest before engaging their services.
14. Final Thoughts
Preparing for retirement is a long-term process, not a one-time financial decision. You do not need to solve every detail immediately. Start by understanding your expected expenses, reviewing available retirement accounts, and choosing a savings amount that fits your current budget.
As your income and circumstances change, you can increase contributions, review your investments, and update your retirement goals. Consistency, realistic expectations, and informed decisions can help you build a stronger financial foundation for the future.
Frequently Asked Questions
1. When should I start saving for retirement?
Starting when you can afford to contribute is generally helpful because it gives your savings more time to grow. If you are starting later, you can still review your budget, set realistic goals, and explore suitable retirement savings options.
2. How much of my income should I save for retirement?
There is no universal percentage that works for everyone. The appropriate amount depends on your age, income, retirement goals, current savings, expected benefits, and financial responsibilities. Estimate your needs before setting a target.
3. What is the best retirement savings account?
The best option depends on your country, eligibility, tax situation, employer benefits, investment choices, fees, and withdrawal rules. Compare available workplace and personal retirement plans before choosing.
4. Can I save for retirement with a small income?
Yes. You can begin with an affordable contribution and increase it when your income or budget allows. A realistic amount saved consistently is often easier to maintain than an unrealistic target.
5. Should I pay off debt or save for retirement first?
It depends on the interest rate, available employer matching, emergency savings, and your financial situation. High-interest debt may deserve priority, but consider the value of any employer retirement contributions before deciding.
6. Are retirement investments guaranteed to grow?
No. Investments can rise or fall in value, and past performance does not guarantee future results. Understand the risks, fees, and time horizon of each investment before committing money.
7. How does inflation affect retirement savings?
Inflation reduces purchasing power over time. This means the amount of money needed to maintain a particular lifestyle may increase during your working years and retirement.
8. Should I work with a financial adviser for retirement planning?
A qualified financial professional may be useful if you have complex accounts, pension arrangements, tax questions, or withdrawal decisions. Review their credentials, fees, and potential conflicts before working with them.
Meet the Author
Bruce Lee
Bruce Lee is the author behind Nksaas. He focuses on creating accessible personal finance content covering budgeting, saving, credit basics, side hustles and beginner investing concepts.
Email: info.nksaas@gmail.com